
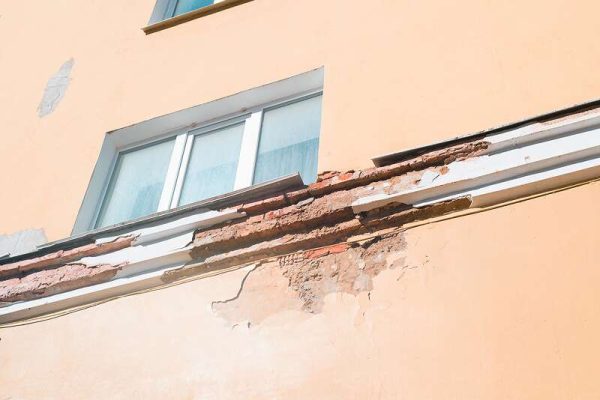
A crack appears in the wall of a five-year-old new build. It runs along a load-bearing section, and no snagging inspection could have picked it up when the property was handed over. The fault was there from the start, hidden inside the structure, and it has only just become visible.
This is a latent defect. It is very different from the scuffed paintwork or sticking door that gets flagged during a final walkthrough. Latent defects stay hidden until long after completion, sometimes for years, and when they surface the repair bill can be substantial.
This guide explains what a latent defect is, what latent defects insurance covers, what the Latent Damage Act 1986 does and does not do, and who pays for cover. If you are a developer, contractor, self-builder or property owner trying to work out where your responsibilities start and end, this should give you a clear answer.
What Is a Latent Defect?
A latent defect is a fault in the design, materials or workmanship of a building that exists at completion but cannot be discovered through a reasonable inspection at that time. It is hidden within the structure rather than sitting on the surface, and it only becomes apparent once it causes visible damage, sometimes many years later.
This matters because it changes who can reasonably be blamed and when. Nobody signed off on a building with a known fault. The problem was there from the start, and nobody could have spotted it without opening up the structure.
What Are Latent Defects? Common Examples
Latent defects can affect almost any part of a building, but the most common and costly examples include:
- Foundation movement caused by poor ground preparation or inadequate foundation design
- Roof truss or structural frame failure due to a design or calculation error
- Waterproofing or tanking failure below ground level
- Structural cracking caused by substandard materials
- Corroded reinforcement hidden within concrete
- Missing or incorrectly installed cavity barriers and fire stopping
- Defective drainage hidden beneath slabs
None of these would show up on a standard inspection at completion. That is exactly the problem latent defects insurance is designed to solve.
Latent Defects vs Patent Defects
The easiest way to tell these apart is to ask whether a competent inspector could have found the problem at handover.
- Patent defects – visible or detectable through normal inspection. Think chipped tiles, a door that will not close properly, or a visible gap in flashing.
- Latent defects – hidden within the structure or its materials. They cannot be found without invasive investigation, and they only show themselves once the building has been in use for some time.
Patent defects are usually picked up and fixed during the defects liability period, often the first 12 to 24 months after completion. Latent defects, by definition, are not. Our guide on how long builders are liable for their work in the UK explains how these periods fit together.
What Does Latent Defects Insurance Cover?
Latent defects insurance, sometimes called inherent defects insurance or structural warranty cover, pays for the cost of repairing hidden structural faults that appear after completion.
Crucially, it is a first-party policy. The person claiming does not need to prove that a contractor was negligent or chase them through the courts. The insurer pays based on the damage itself, not on who is at fault.
Most policies cover:
- Foundations and the load-bearing structure
- Roof structure and covering
- Structural waterproofing
- Resultant damage caused by a covered structural failure
Some more comprehensive policies also cover non-structural elements, such as mechanical and electrical services, drainage or lifts, though this varies by provider and project.
What is usually excluded:
- Known defects present before the policy started
- General wear and tear
- Damage caused by poor maintenance
- Cosmetic or non-structural snagging issues
Cover is arranged at or before practical completion and typically runs for 10 to 12 years from completion, with some providers offering longer terms. You can read more about how these policies work in our guide to 10-year structural warranties.
The Latent Damage Act 1986 Explained Simply

There is a lot of confusion around this legislation, partly because it gets called different things. There is no “Latent Defects Act”. The correct name is the Latent Damage Act 1986, and it amended the Limitation Act 1980 by adding new rules for negligence claims involving hidden damage.
Under the standard rules, you generally have six years from the date the damage occurred to bring a negligence claim. The problem with latent defects is obvious: if the damage is not discovered until year eight, that six-year window may have closed before anyone even knew there was a problem.
The Latent Damage Act 1986 fixes this by giving claimants an alternative period of three years from the date they knew, or reasonably ought to have known, about the damage. There is a final backstop, though. No negligence claim can be brought more than 15 years after the negligent act or omission that caused the damage, no matter when it was discovered.
So in short, you can bring a claim within:
- Six years from when the damage occurred, or
- Three years from when you discovered it, if that ends later
- Subject to an overall longstop of 15 years from the original negligent act
Why the Act Alone Is Not Enough
Having a longer window to sue sounds reassuring, but it only helps if there is someone left to sue. A contractor can go out of business long before a latent defect surfaces. Proving negligence takes time, costs money, and is never guaranteed to succeed even when the fault seems obvious.
This is exactly the gap latent defects insurance fills. Instead of relying on a legal right that depends on tracking down a solvent contractor and proving fault, the policyholder claims directly against the insurer. The building owner gets the repair funded, and the insurer can pursue recovery from whoever was responsible if it chooses to.
Latent Defects and the Building Safety Act 2022
The Building Safety Act 2022 made significant changes to how long people can bring claims about defective homes. It extended the limitation period under the Defective Premises Act 1972 from six years to 15 years for claims arising after 28 June 2022, and to 30 years retrospectively for claims that arose before that date.
For developers and contractors, this means potential liability for defects in residential work now stretches much further into the future than it used to. That makes having robust latent defects or structural warranty cover in place even more important, both to protect owners and to protect the business against claims that could surface many years after a project is finished.
Who Pays for Latent Defects Insurance?
In most cases, the developer or main contractor arranges and pays for the policy before the project reaches practical completion. The premium is usually a single upfront payment that is built into the overall project budget rather than billed separately to the eventual owner.
Premiums have historically been quoted at around 1.3% to 1.7% of the rebuild cost, though pricing has become more competitive as more providers have entered the market.
Mortgage lenders are a major driver of demand. Most UK lenders require latent defects or structural warranty cover before they will lend on a new build property, particularly where the building is under 10 years old. Without it, a developer may struggle to sell units at all, since buyers relying on a mortgage will not be able to complete.
Who Needs Latent Defects Insurance?
- Developers building new residential or commercial schemes, see our property developers insurance page
- Self-builders, particularly where a mortgage, remortgage or future sale is likely, see our guide to self-build insurance
- Housing associations and registered providers delivering social housing
- Funders and investors who want protection against structural risk
- Developers of conversions, where lenders often require cover just as they would for a new build
Example in Practice
Go back to the crack in the five-year-old wall. If latent defects insurance is in place, the owner submits a claim, an assessor confirms the fault meets the policy definition, and the insurer funds the repair. No court case, no need to track down the original contractor, no argument about who was negligent.
Without a policy, the owner is left relying on the Latent Damage Act 1986 or the Defective Premises Act. That means proving the defect was caused by negligence or poor work, identifying who was responsible, checking whether they are still trading, and potentially pursuing a claim through the courts, all within limitation periods that can be difficult to calculate precisely.
Get the Right Cover Sorted Before Practical Completion
Timing matters. Latent defects insurance needs to be arranged before or at practical completion, and in most cases before work starts on site, because many providers need to inspect the build as it progresses. Once a defect is known about, it cannot be covered retrospectively.
For developers, that means treating latent defects insurance as a standard part of project planning, not an afterthought once a lender asks for proof of cover. For self-builders, it means checking early whether a future sale or remortgage will require this type of policy.
If you want tailored advice on arranging building warranties or latent defects cover for your project, you can get a quote from our team.
Frequently Asked Questions
What is the difference between a latent defect and a patent defect?
A patent defect is visible or detectable at completion through normal inspection. A latent defect is hidden and only becomes apparent later, often years after the building is in use.
Does the Latent Damage Act 1986 mean I do not need latent defects insurance?
No. The Act extends the time you have to bring a legal claim, but it does not guarantee there is a solvent party to sue or that negligence can be proven. Insurance provides direct cover without needing to establish fault.
How long does a latent defects insurance policy last?
Most policies run for 10 to 12 years from practical completion, although some providers offer longer terms.
Who is responsible for arranging latent defects insurance?
Usually the developer or main contractor, before the project reaches practical completion and often before work starts. The cost is typically built into the overall project budget.
Is latent defects insurance a legal requirement?
Not in the strict sense, but most UK mortgage lenders will not lend on a new build without it, which makes it essential in practice for most residential developments.